Best high-yield savings accounts in Dubai & the UAE (brokers & banks)

In the United Arab Emirates (UAE), banks offer a wide range of savings accounts tailored to meet the needs of residents and expatriates. You will find savings accounts both in AED and USD, including Sharia-compliant savings accounts.
In this article, we will explore the top savings accounts offered by brokers and traditional banks in the UAE, analyzing their interest rates, minimum and maximum balance requirements, eligibility criteria, and other essential features.
Quick comparison table
| Platform/account | Interest rate (AED/USD) | Min/max Balance | Main benefit |
|---|---|---|---|
| Mashreq NEO Plus Saver | Up to 6.25% (AED) | AED 50k (max 500k) | Top yield + cashback |
| ADCB Super Saver | Up to 5.50% (AED) | AED 50k | Bonus rate on new-to-bank funds |
| Wio | 3.25% flexible / 6.00% fixed 1 month (AED) | Salary ≥ AED 15k | Salary-linked high interest |
| FAB iSave | 5.60% (AED) – promotion until 31 Dec 2026 | None | No withdrawal limits |
| Sarwa Save | 3.7% projected (USD), before a 0.5% fee | None | Flexible and Sharia option |
| Trading 212 | 3.3% (USD) | None | Unlimited withdrawals |
| eToro | 0.5% to 3.55% (USD) | From USD 10,000 total balance | Instant withdrawals |
| Interactive Brokers | 2.840% (AED); 3.130% (USD) | AED 35k / USD 10k | Brokerage-linked savings |
Note: All interest rates are annualized for USD and AED deposits and can change with market conditions. Always check if a rate is promotional (temporary) or requires a premium plan. Explore the companies mentioned and decide by yourself!
Top picks for different needs
- Highest AED Interest Rate: Mashreq NEO Plus Saver - Up to 6.25 % p.a. when you transfer a monthly salary of ≥AED 10k (5% if you simply keep ≥ AED 50k on deposit).
- Most Flexible AED Account (No Minimum, Unlimited Access): FAB iSave. The current promotion pays 5.60% p.a. on new funds deposited between 1 September 2026 and 31 December 2026 - no minimum balance, no lock-ins, and unlimited withdrawals.
- Best USD Yield: Sarwa. Perfect for expats or investors who already hold USD and want interest without sacrificing liquidity. New users can earn a signup bonus with the code RLLAA29D.
- Best Sharia-compliant option: Sarwa Save Halal. A projected return of about 4.0% p.a. before fees through the Emirates Islamic Money Market Fund, with no minimum balance, regulated by ADGM's FSRA. Sarwa charges a 0.5% annual management fee on both Save+ and Save Halal, so the net projected return is roughly 3.2% and 3.5% respectively. These are money market fund returns, not a fixed interest rate, and they move with short-term US rates.
Tip: Because the UAE dirham is pegged to the US dollar, holding USD in broker platforms (eToro, Sarwa, IBKR) carries minimal FX risk for day-to-day spend in AED - but not zero.
Depth dive on the savings accounts in the UAE
Mashreq (NEO Plus Saver)
- Interest rate: Up to 6.25% (AED)
- Min/Max balance: AED 50,000 (max AED 500,000)
- Eligibility: UAE residents with Emirates ID; salary transfer or balance requirement
- Main benefit: Top yield + cashback

Mashreq Bank, one of the UAE’s oldest and fastest-growing digital banks, launched the NEO Plus Saver savings product in mid‑2025. Targeting both salaried and non‑salaried customers, it offers a 6.25% p.a. interest for those transferring a monthly salary of AED 10,000 or more via Mashreq NEO, plus up to AED 5,000 in initial cashback bonuses.
Customers who can’t transfer their salary can still earn 5% p.a. interest by maintaining a minimum balance of AED 50,000. Withdrawals are flexible (up to two free debits per month without losing interest), and interest is paid monthly on balances up to AED 500,000.
The entire account opening process is fully digital via the Mashreq Mobile App, providing access to fee‑free US stock trading, mutual funds, bonds, and more
How to start earning interest?
- Step 1: Open a Mashreq NEO Account, if you don’t have one.
- Step 2: Once your account is activated, open a NEO PLUS Saver Account through Mashreq Mobile App instantly.
- Step 3: Transfer your salary (at least AED 10,000) to Mashreq NEO or keep balance of at least AED 50,000.
- Step 4: Move money from your NEO Account to your NEO PLUS Saver Account to start earning interest.
Mashreqbank PSC is licensed and regulated by the Central Bank of the United Arab Emirates (CBUAE), under its banking supervision and licensing framework.
ADCB (Super Saver)
- Interest rate: Up to 5.5% (AED)
- Min/Max balance: AED 50,000
- Eligibility: UAE residents; bonus rate requires new-to-bank funds
- Main benefit: Bonus rate on new-to-bank funds
ADCB (Abu Dhabi Commercial Bank) is one of the UAE’s leading banks, known for its strong digital services and customer-focused offerings.
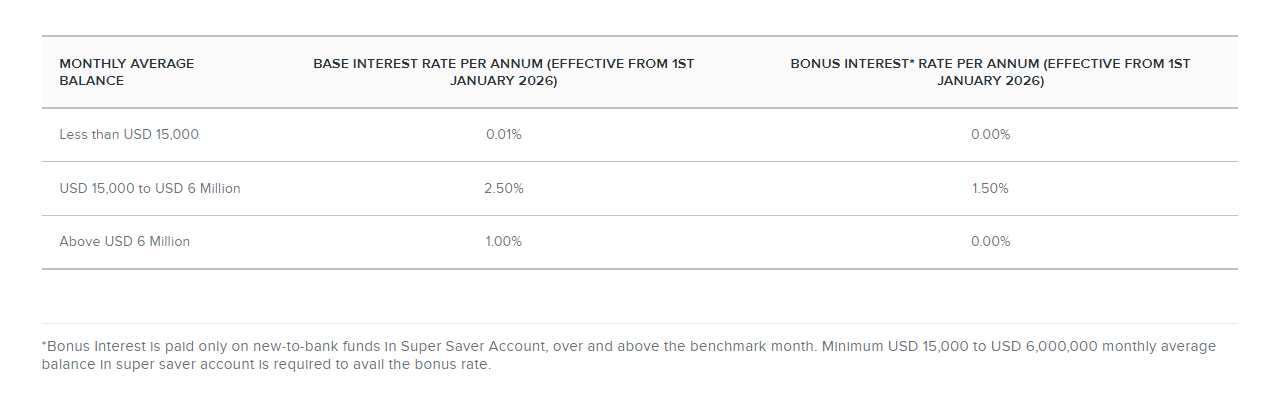
The Super Saver Account pays up to 5.5% p.a. on AED balances: a base rate of 2.25% p.a. (effective 1 May 2026) plus a bonus rate of 3.25% p.a. (effective 1 September 2026) on monthly average balances between AED 50,000 and AED 20 million. Below AED 50,000 the rate drops to 0.01%, and above AED 20 million the base rate is 1.00% with no bonus. The same 2.25% + 3.25% structure applies in USD, from USD 15,000 to USD 6 million. The bonus is paid only on new-to-bank funds above the benchmark month (currently March 2026) — internal transfers from existing ADCB accounts do not qualify, and the new money must raise your total relationship balance. Interest is paid monthly. The account also offers seamless digital onboarding and is ideal for UAE residents seeking competitive savings rates from a well-established, fully regulated bank.
After the promotion, these are the base rates (AED):

In USD:
ADCB (Abu Dhabi Commercial Bank PJSC) is fully licensed and regulated by the Central Bank of the United Arab Emirates (CBUAE), which oversees all conventional and Islamic banks operating onshore in the UAE
Wio (digital bank – ADQ, Alpha Dhabi, e& and FAB)
- Interest rate: 3.25% flexible / 6.00% fixed 1 month (AED)
- Min/Max balance: Salary ≥ AED 15,000
- Eligibility: UAE residents with Emirates ID
- Main benefit: Salary-linked high interest

Wio Bank PJSC is owned by ADQ and Alpha Dhabi Holding (65% combined), e& (25%) and First Abu Dhabi Bank (10%), and is licensed and regulated by the Central Bank of the UAE. Launched in 2022, it offers app-based personal and business banking tailored to UAE residents.
The Salary Plan is open to customers transferring a salary of at least AED 15,000 (AED 5,000 for partner companies) within two months. It pays 3.25% p.a. on flexible Saving Spaces with no lock-in and no minimum deposit, and 6% p.a. on one-month Fixed Saving Spaces provided you also spend at least AED 5,000 a month. Interest-earning balances are capped at AED 1.5 million with one salary transfer, or AED 2.5 million where both account leads transfer a salary. Cashback runs up to 2% on Wio Credit purchases, 1% on international spend from your own funds and 0.5% on local AED debit spend, capped at AED 2,500 a month in total. Withdrawals and transfers remain flexible and digital-first.
Note that the 6% rate only applies to a one-month fixed term and carries a minimum monthly spend condition, so we highlight the 3.25% flexible rate as the realistic ongoing return.

Wio Bank is fully licensed and regulated by the Central Bank of the UAE, adhering to consumer protection standards, financial integrity rules, and security provisions set by the CBUAE
FAB (iSave)
- Interest rate: 5.60% (AED) – promotion on new funds, 1 September to 31 December 2026
- Min/Max balance: None
- Eligibility: UAE residents
- Main benefit: No withdrawal limits

FAB, formed in 2017 through the merger of First Gulf Bank and National Bank of Abu Dhabi, is the largest bank in the UAE by assets and is widely recognized for its digital banking excellence.
The iSave Account is an online-only savings account. FAB currently pays 5.60% p.a. on new funds deposited between 1 September 2026 and 31 December 2026, with no minimum balance and no limit on withdrawals. The customer's overall balance as at 31 August 2026 is the base balance, so only fresh money earns the campaign rate. New funds from the previous campaign (1 May 2023 to 31 August 2026) keep earning 4% p.a. Outside the campaign, the product's own tiered rates apply: up to 2.465% p.a. on balances below AED 500,000, 2.465% to 3.251% between AED 500,000 and AED 5,000,000, and 3.251% or lower above AED 5,000,000. Campaign interest is paid within 45 days of the campaign end date.
FAB is fully licensed and regulated by the Central Bank of the UAE (CBUAE), which oversees its compliance with banking laws, capital adequacy, consumer protection, and financial crime standards.
Sarwa (Sarwa Save)
- Interest rate: 3.7% (USD)
- Min/Max balance: None
- Eligibility: UAE residents (via Sarwa app)
- Main benefit: Flexible & Sharia option

Sarwa Digital Wealth (Capital) Limited is a UAE‑based fintech platform (founded in 2017, headquartered in Abu Dhabi) offering a suite of financial services, including Sarwa Save which provides a cash‑management fund offering estimated returns (e.g., 3.7% for Save+ or 4.0% for Halal variant), with no lock‑in, no minimum balance, and zero withdrawal fees.

Sarwa Digital Wealth (Capital) Limited is regulated by the Financial Services Regulatory Authority (FSRA) of the Abu Dhabi Global Markets (ADGM) under a Category 3C licence that covers retail and investment money activities.
Sarwa is not a bank. Sarwa's help centre states that investable cash and securities in Sarwa Save are held in a custodian account at the Denmark-domiciled Saxo Capital Markets, where they ultimately sit with custodians such as Citibank. These arrangements keep client assets separate from Sarwa's own corporate accounts.
Trading 212
- Interest rate: 3.3% (USD)
- Min/Max balance: None
- Eligibility: Open to UAE residents via global platform
- Main benefit: Unlimited withdrawals

Trading 212 is a UK-based fintech brokerage founded in 2004, offering commission‑free trading in stocks, ETFs, and CFDs, along with fractional shares and automated portfolio tools like “Pies” and AutoInvest.
You also have access to a debit card, cashback on your spending and interest in several currencies. Unfortunately, AED is not one of them.
In the UAE, Trading 212 operates under the subsidiary “Trading 212 UK Ltd”, regulated by the UK’s Financial Conduct Authority (FCA), offering compensation of up to £85,000 via the Financial Services Compensation Scheme (FSCS).
Want to know more? Check our in-depth Trading 212 review.
eToro
- Interest rate: Up to 3.55% (USD)
- Min/Max balance: Total balance of at least USD 10,000
- Eligibility: Available globally, UAE residents included
- Main benefit: Instant withdrawals

eToro is a global multi‑asset investment platform founded in 2007, with over 30 million users worldwide. It offers commission‑free trading for ETFs and low commissions on cryptocurrencies, CFDs, forex, indices, and commodities (supports fractional shares).
eToro allows you to earn interest on uninvested USD balances, giving you passive earnings directly in your account with monthly payments (Interest is paid into your eToro balance every month) and no lock-in (funds remain fully liquid; withdraw at any time).
Your total balance decides which rate you qualify for, but the interest itself is paid only on your available USD cash balance. eToro defines total balance as your total realised equity — invested positions plus available cash. For clients outside the EU and UK, which includes UAE residents on eToro (ME) Limited, the tiers are 0.5% from USD 10,000, 2.25% from USD 25,000, 3.25% from USD 50,000 and 3.55% from USD 250,000. Below USD 10,000 no interest is paid. Interest is not automatic: entitlement follows your eToro Club tier and you have to switch on “Interest on USD Cash Balance” in the eToro Club dashboard.

eToro is available in the UAE through eToro (ME) Limited, regulated by ADGM’s FSRA.
eToro also offers welcome bonuses for UAE users.
Want to know more? Check our in-depth eToro review.
Interactive Brokers (IBKR)
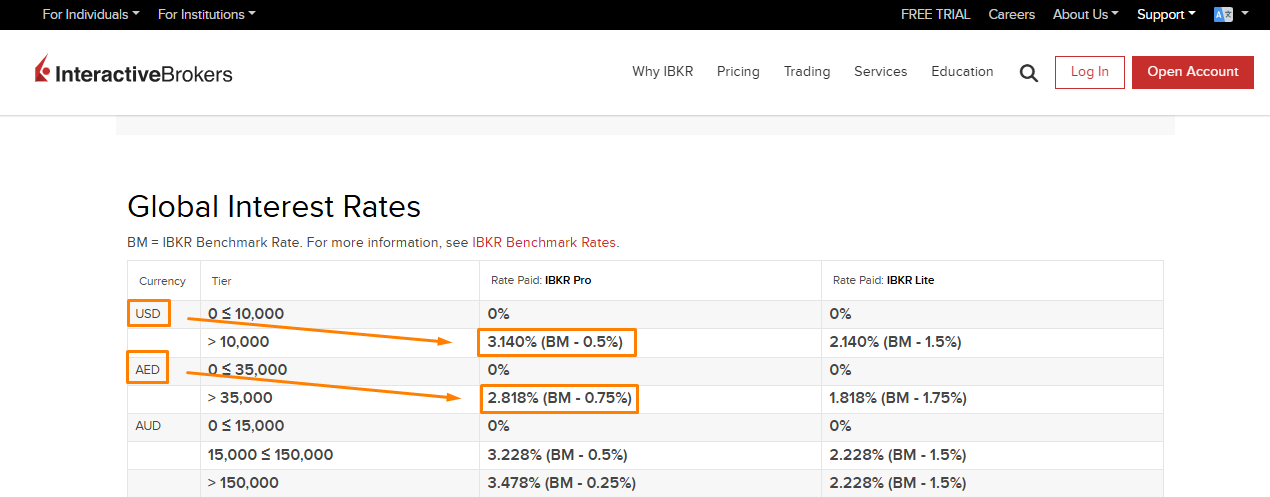
- Interest rate: 2.840% (AED); 3.130% (USD)
- Min/Max balance: AED 35,000 / USD 10,000
- Eligibility: Available globally, UAE residents included
- Main benefit: Brokerage-linked savings
Interactive Brokers Group, Inc. is a U.S.-based multinational brokerage founded in 1978, headquartered in Greenwich, Connecticut. It serves over 3.3 million clients worldwide, offering direct-access trading across equities, options, futures, forex, bonds, ETFs, CFDs, crypto, and more.
Interest is tier-based, payable only for idle balances above minimum thresholds:
- USD: no interest on the first USD 10,000; balances above that earn up to 3.130% (benchmark rate minus 0.5%)
- AED: no interest on the first AED 35,000; above that, up to 2.840% (benchmark rate minus 0.75%)
These are the top rates, payable on accounts with a net asset value above USD 100,000. Smaller accounts earn a reduced rate that scales up as NAV approaches USD 100,000.
The entity operating locally is Interactive Brokers (U.K.) Limited – DIFC Branch, which is regulated by the Dubai Financial Services Authority (DFSA) under DFSA register F008423, authorised to arrange deals in investments and custody within DIFC.
Want to know more? Check our Interactive Brokers review.
Overview of the UAE savings market
The UAE savings market continues to be shaped by a combination of macroeconomic conditions and competitive deposit rate offerings, which are largely influenced by the Central Bank of the UAE (CBUAE) base rate and the Emirates Interbank Offered Rate (EIBOR).
Interest rate environment
- CBUAE Base Rate: As of 14 September 2026, the CBUAE base rate on the Overnight Deposit Facility stands at 3.65%, held steady at the April, June and July 2026 decisions. It tracks the US Federal Reserve's IORB rate because the dirham is pegged to the dollar.
- EIBOR: The 3-month EIBOR is around 4.14% (14 September 2026), above the base rate — the base rate anchors overnight money, while term rates carry a premium. This interbank funding cost is what drives the pricing of savings and deposit products, which is why the best AED savings rates sit above the base rate.
- Savings yields: Headline retail deposit rates in the UAE currently range from about 2.5% on standard tiered balances to 6.00% on the best salary-linked and promotional accounts, with most competitive AED offers landing between 3% and 5.6%.
This alignment between the CBUAE base rate and EIBOR creates a highly competitive environment for depositors, as financial institutions adjust their rates to attract liquidity while maintaining healthy net interest margins.
UAE retail investor landscape
- High savings propensity: According to a Visa market survey published in June 2024, nearly half (48%) of investors had been saving by building up a balance in their bank account over the preceding 12 months, with savings accounts and fixed deposits remaining the most popular vehicles.
- Preference for liquidity: A significant portion of UAE retail investors demonstrate short holding periods: 33% hold investments for months, 22% for weeks, and 7% for days, implying a substantial inclination toward liquid or cash-equivalent investment behavior rather than long-term vehicles
- Response to rates: Retail investors have shown high sensitivity to changes in interest rates, with deposit inflows increasing significantly when rates exceed the 4% threshold, closely tied to the CBUAE base rate and EIBOR movements.
Banks vs. Brokers: Key differences
In the UAE, savings products are offered by two main types of institutions: traditional banks and brokerage or fintech platforms. Understanding the distinction is crucial:
| Feature | Banks | Brokers/Fintech |
|---|---|---|
| Regulator | Central Bank of the UAE (CBUAE) | FSRA (ADGM), DFSA (DIFC), FCA (UK) |
| Deposit Protection | No operational depositor-compensation scheme; CBUAE prudential supervision and a strong record of state support | No UAE deposit protection; relies on custodian arrangements or international schemes (e.g. FSCS in the UK) |
| Currency Options | Mainly AED and USD | Primarily USD; some offer AED (e.g. Interactive Brokers) |
| Access | Requires Emirates ID and residency | Often available globally; some accept UAE residents without Emirates ID |
| Liquidity | Free withdrawals (some with monthly limits) | Full liquidity; usually no withdrawal penalties |
| Extra Benefits | Salary-linked perks, cashback, local ATM network | Trading features, higher USD rates, global diversification |
When to choose a bank: If you need AED savings, local salary transfer features, or want a purely regulated UAE banking product.
When to choose a broker: If you hold USD savings, want higher flexibility, or combine investing with savings.
Eligibility for non-residents and expatriates
Eligibility varies significantly depending on the platform:
Banks
- Emirates ID required: Most banks (e.g. Mashreq, ADCB, FAB, Wio) require UAE residency.
- Salary transfer: Some banks (e.g. Mashreq NEO Plus Saver, Wio Salary Account) require a monthly salary transfer to unlock the highest rates.
- Promotions on new money: Certain rates (e.g. the ADCB Super Saver bonus) apply only to new-to-bank funds, not to money already held at the bank.
Brokers
- Available globally: Platforms like Interactive Brokers, eToro, and Trading 212 allow UAE residents to open accounts online without needing a UAE salary transfer.
- Expat-friendly: Sarwa Save (regulated in ADGM) is specifically designed for UAE residents, including expatriates, and has no minimum deposit requirement.
- Non-residents: Some brokers accept clients from outside the UAE, but interest in AED is usually unavailable; USD is the default.
Risks and safety considerations
When choosing between banks and brokers, safety is a top priority. Here’s how each is regulated and how your money is protected:
Banks (CBUAE)
- Licensed and supervised by the Central Bank of the UAE (CBUAE).
- Capital adequacy requirements ensure banks maintain sufficient reserves.
- The UAE has no operational deposit guarantee scheme paying a fixed amount per depositor per bank. The Central Bank Law empowers the CBUAE Board to create one — the power is discretionary and sets no monetary limit — but it has not been exercised. What protects depositors today is prudential supervision, capital adequacy requirements and the authorities' record of supporting banks under stress, as in 2008 when the UAE government guaranteed deposits in UAE banks. It is not an FDIC-style or EU-style guarantee, and the UAE is not a member of the International Association of Deposit Insurers.
- Banks also follow strict anti-money laundering (AML) and consumer protection rules.
Brokers
- ADGM (FSRA) or DIFC (DFSA) regulation applies to local UAE branches (e.g. Sarwa, Interactive Brokers DIFC).
- International protections may apply for foreign entities:
- Trading 212 UK: Covered by the UK’s FSCS, which protects up to GBP 85,000.
- Interactive Brokers: Uses segregated custodial accounts and is regulated in multiple jurisdictions.
- Custodian banks: Sarwa Save assets are held via a custodian account at Saxo, with underlying custodians such as Citibank, separate from Sarwa's operating accounts.
Currency risk
If you save in USD but your expenses are in AED, exchange rate changes can impact your effective return. However, because the AED is pegged to the USD, this risk is very low but not entirely zero.
Sharia-compliant savings accounts
For those seeking faith-based financial products, Sharia-compliant savings accounts are a growing segment in the UAE. These accounts follow Islamic finance principles: no interest (riba) is paid. Instead, profit-sharing or other Sharia-compliant structures are used.
Examples:
- Sarwa Save Halal:
- Regulated by FSRA in ADGM.
- Provides a Sharia-compliant alternative to its USD cash product (around 4.0% expected return).
- Uses Islamic money market funds that comply with Sharia rules.
- Emirates Islamic and ADIB:
- Offer profit-bearing savings accounts (AED and USD) where returns come from Islamic financing contracts (e.g. mudarabah).
- Fully regulated by CBUAE.
Bottom line
Saving money in the UAE has never been more rewarding, with options ranging from traditional banks offering competitive AED interest rates to brokerage platforms providing flexible USD-based returns.
Choose based on your income currency, residency status, risk tolerance, and liquidity needs. While banks provide local security and AED-based stability, brokers offer higher USD returns and global accessibility. A blended approach can be the most effective strategy in 2026.