Best financial advisors in Dubai & the UAE (and which to avoid)

The financial advisory industry in Dubai and the wider UAE has a mixed reputation - some firms provide solid, regulated advice, but many others are sales-driven and push costly long-term plans.
Exacerbating the issue, strict defamation laws mean you rarely see bad reviews online (even honest criticism can lead to legal trouble). This guide will walk you through how to pick a properly regulated, fee-transparent adviser, the specific red flags to avoid, and some top advisors to consider (as well as popular alternatives like robo-advisors or DIY investing).
Disclaimer: BrokerMatch is not affiliated with any financial advisor. Please check their credentials, contact the firms and do your own research.
Licences, fees and firm details in this guide were last verified against the DFSA, ADGM FSRA and UAE CMA public registers on 16 September 2026. Registers change — always check the live entry before you engage a firm. No firm named in this guide appears on any UAE regulator’s warning or violation list as a wrongdoer. Two adjacent findings are worth recording: the DFSA has twice alerted the public to fraudsters impersonating GSB Capital Ltd, and the ADGM FSRA register lists four regulatory actions against Sarwa Digital Wealth (Capital) Limited, including a May 2024 Final Notice concerning an offer of securities without an approved prospectus.
Best financial advisory companies in the UAE (shortlist to research)
Based on online information and expat community feedback, here are several advisory firms in the UAE that are often recommended (do your own due diligence on each):
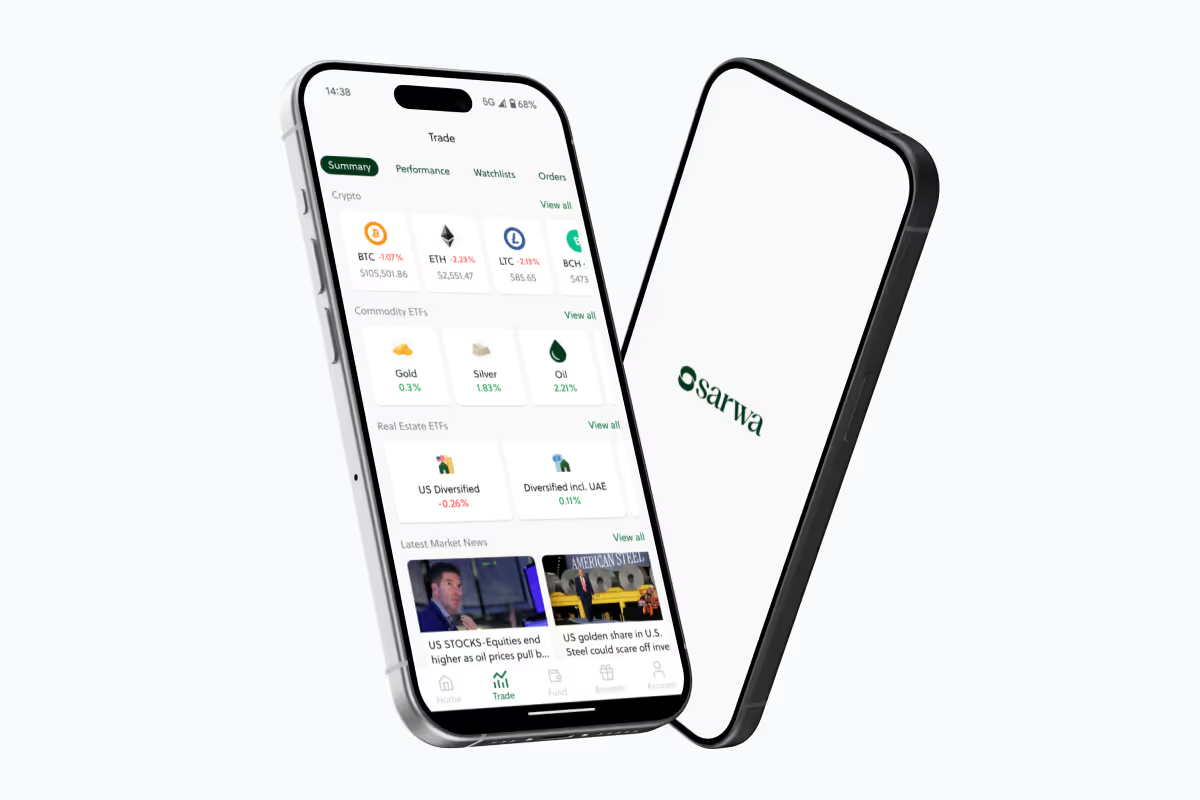
- Sarwa: The best financial advisory service in the UAE overall. The leading robo-advisor platform in the UAE, which also offers a human-assisted private wealth service. Sarwa Invest charges a tiered annual management fee assigned by account balance: 0.85% below USD 100,000, 0.7% from USD 100,000 to USD 500,000, 0.5% above USD 500,000 and 0.4% above USD 5,000,000. In the entry tier Sarwa charges the greater of the calculated monthly fee or USD 7, so small portfolios pay the USD 7 monthly minimum — on a USD 1,000 balance that is roughly 8.4% a year, not 0.85%. The minimum is waived for the first three months. Sarwa Trade is separate, at $1 or 0.25% per trade. Group entities include Sarwa Digital Wealth (Capital) Limited (ADGM, FSRA FSP 190037 — the entity retail clients contract with) and Sarwa Investment Management Limited (DIFC, DFSA ref F003607, which holds a Managing Assets permission but no Retail Client endorsement). A third entity, Sarwa Digital Wealth Limited (DIFC), had its DFSA licence withdrawn in June 2024. New users earn a welcome bonus.
- Vault: Private wealth management company based in the UAE, great if you also value a digital experience. ADGM/FSRA registered, as "Vault Wealth Limited". Its advised tiers start at $100,000 ("Priority"), rising to "Private" ($1m–$5m) and "Family Office" ($5m+). It offers a digital platform alongside human advisory, and is fee-only — it states it takes no retrocessions, kickbacks or placement fees. Note that Vault holds an advising-and-arranging permission and is not permitted to hold or control client assets: your portfolio is custodied in your own name at a third-party custodian.
- St. James’s Place (SJP): A FTSE 100 wealth management firm from the UK, now fully licensed in the DIFC and regulated by the DFSA. SJP is one of the largest wealth managers globally, managing £240.8 billion for 1,064,000 clients as at 30 June 2026. Its DIFC entity is St. James’s Place (Middle East) Limited (DFSA ref F003486), licensed to advise and arrange — it does not hold a Managing Assets permission. It is best for UK and Australian expats.
- Atlas Wealth Management: A specialist in Australian expat financial advice and cross-border planning. Its UAE entity is Atlas Wealth Management (DIFC) Limited, DFSA licence F005228, authorised since February 2020 to advise and arrange for retail clients. Atlas states it is the only Australian firm dual-licensed in both Australia (ASIC, AFSL 557000) and the UAE. They focus on helping Australian expatriates navigate the complex tax, superannuation, and pension landscape between Australia and the UAE.
- Progeny (DIFC) Limited (formerly The Fry Group) (DFSA-authorised, ref F009864). Progeny announced its acquisition of The Fry Group in June 2022 and the brand has now been retired: the old DIFC entity, Wilfred T. Fry (Personal Financial Planning) Limited, had its DFSA licence withdrawn on 27 January 2026 and the UAE business now sits in Progeny (DIFC) Limited, licensed 16 June 2025. Still particularly known for expertise in cross-border tax and estate planning, especially for UK expats.
- GSB Capital (GSB Group): A full-service wealth management and corporate advisory firm headquartered in the DIFC. GSB is regulated by the DFSA in the UAE (ref F006321, licensed April 2021) and by the UK’s FCA. Note that the DFSA has twice issued public alerts about fraudsters impersonating GSB Capital Ltd using fake websites and real employee names, most recently in December 2025, and the FCA has published a clone-firm warning about a site impersonating the authorised firm. These are warnings about fraudsters, not about GSB itself — but verify any contact against the DFSA public register before engaging.
Here’s a quick comparison based on online information:
| Advisor | Regulator (UAE) | Minimum Investment | AUM (approx.) | Fees (indicative) | Notes |
|---|---|---|---|---|---|
| Vault Wealth | ADGM (FSRA) – Vault Wealth Limited, FSP 220092 (advising and arranging only; not permitted to hold or control client assets) | $100,000 entry point for its advised "Priority" tier | Not disclosed | Marginal tiers: 1.25% on the first $100k, 1.00% on the next $400k, 0.50% on the next $500k, 0.25% above $1m, nil above $20m — about 0.78% blended on a $1m portfolio | Fee-only advisory with digital platform; assets custodied in the client's own name at a third-party custodian. |
| Sarwa (robo-advisor) | ADGM (FSRA) / DIFC (DFSA) | $500 | $1bn+ (May 2026) | Invest: 0.4%–0.85% p.a. by balance (min. $7/month in the entry tier) | Automated ETF investing; simple app; regulated locally. |
| St. James's Place (SJP) | DIFC (DFSA) – St. James's Place (Middle East) Limited, ref F003486 | n/a | £240.8bn (30 Jun 2026, global) | Initial advice 3% on first £250k / 2% next £250k / 1% above £500k, capped at £30,000; ongoing advice 0.80% p.a.; ongoing product charge 0.27%–0.35%; fund charges 0.09%–0.69%. Early Withdrawal Charges no longer apply to new investments (removed 26 Aug 2025; legacy EWC terms still run off for existing clients). | FTSE 100 firm, large scale and comprehensive offering. |
| Atlas Wealth Management | DIFC (DFSA) – Atlas Wealth Management (DIFC) Limited, ref F005228 | n/a | n/a | Varies by service (fee/AUM) | Specialist in Australian expat advice (superannuation, pensions, tax). |
| GSB Capital (GSB Corp) | DIFC (DFSA) – ref F006321 | n/a | n/a | Varies by service (fee/AUM) | Private wealth and corporate advisory; strong Dubai presence. |
| Progeny (DIFC) Limited (formerly The Fry Group) | DIFC (DFSA) – ref F009864 | n/a | n/a | Varies by service (fee-based) | Tax-led planning for expats. The former Fry Group DIFC entity had its licence withdrawn on 27 January 2026; the UAE business now sits in Progeny (DIFC) Limited. |
Financial coaches in the UAE (for DIY investors)
Many UAE residents invest via low-cost ETFs and robo options, sometimes with one-off coaching.
Coaching is education, not regulated advice in the UAE - use it to improve your plan, then implement via a regulated platform.
Here is a reputable financial coach in the UAE:
- Steve Cronin, from DeadSimpleSaving. Offers private coaching and courses for expats.
Coaching helps if you prefer DIY and want accountability without handing over your portfolio.
Choose a regulated firm
If you need a regulated, advice-led firm (complex cases, pensions, cross-border tax), shortlist advisors on the official registers and verify their permissions:
- DIFC (Dubai): DFSA-authorised advisers in the Dubai International Financial Centre (DIFC)
- ADGM (Abu Dhabi): FSRA-authorised firms in Abu Dhabi Global Market (ADGM)
- Onshore UAE: CMA (Capital Market Authority, formerly the Securities & Commodities Authority) licensed companies.
💡 Tip: An office address is not the same as a licence. Regulators explicitly warn that being incorporated locally does not mean a firm is authorised to advise. Always check the public registers.
What a “good” financial advisor looks like
A quality UAE adviser should be able to evidence all of the following before you sign anything:
- Regulatory status & permissions (DFSA/FSRA/CMA) + link to their public register entry.
- Exact fees in dirhams or USD (one-off/retainer/AUM). Avoid vague ranges; insist on a fee schedule and disclosure of any third-party commissions.
- No lock-ins or surrender penalties on the advice engagement.
- Product-agnostic portfolios (low-cost, diversified funds/ETFs) rather than high-margin products.
- Written conflicts-of-interest statement and confirmation they won’t receive product commissions.
Historically, many expat "advisers" would work in the UAE only briefly - some felt free to recommend bad products for quick commission and then leave the country, escaping the fallout. Today, however, an increasing number of advisors see the UAE as a long-term career market, which is raising standards.
Stick to firms that have a stable presence and a track record to lose, since they have more incentive to maintain a good name. Some of the platforms mentioned here are even listed on a stock exchange, which is also a positive sign.
Which to avoid
Please be extremely cautious if you see:
- Cold calls or WhatsApp pitches about “tax-free savings” or “exclusive offshore plans.”
- Guaranteed or target returns (e.g., "20% a year") - this is marketing. If it seems too good to be true, it probably is.
- Advisors who receive commissions for recommending financial products. Avoid these at all costs.
- Long-term “savings plans” (15-25 years) or insurance-linked investment wrappers with bonuses, up-front commissions, and heavy surrender fees. These are widely criticised for high costs and lock-ins.
- Structured notes sold as “safe income” or “capital protected” without a clear downside illustration.
The UAE community has, for years, flagged commission-driven sales and sub-par outcomes versus simple, low-cost portfolios.
Not everyone needs an advisor
Titles like “wealth manager” and “financial architect” can sound impressive, but many salespeople are paid by product commissions, which creates conflicts between their incentives and your outcomes. A smaller set of professionals operate on transparent, client-paid fees and put your interests first - that’s what you want to hire when you genuinely need advice.
If your situation is straightforward, a simple, low-cost index fund portfolio can get you most of the way there.
Keep advisers for complex needs (tax, estates, pensions, business exits), and even then, be cautious if your incentives are aligned.
A large, active UAE community (e.g., SimplyFI) advocates DIY index investing with low costs and simple portfolios, reserving advisers for tax/estate complexity.
Their free guide is a solid resource to get started and understand the industry.
DIY & robo options
If you do go DIY (fully or partially), use regulated platforms:
- Interactive Brokers (IBKR) and other UAE-authorised brokers allow you to invest on your own. It’s a steeper learning curve, but in the long run, it pays off.
- Robo-advice: Firms like Sarwa operate under UAE regulatory oversight. It allows you to invest automatically in global, low-cost portfolios. They also offer a Private Wealth Management service for high-net-worth individuals.
Robo-advisor vs Financial Advisor vs DIY + Coaching
| Option | Best for | Pros | Cons | Typical ongoing cost | Regulation |
|---|---|---|---|---|---|
| Robo-advisor (e.g., Sarwa) | Hands-off investors who want automation and rebalancing | Simple onboarding, diversified ETFs, app experience | Less customisation; advisory fee | ~0.4–0.85% + fund costs, with a monthly minimum on small balances | Firm must be authorised (DFSA/FSRA). |
| Financial advisor | Complex cases (pensions, cross-border tax, estate planning, business owners) | Personalised plan, holistic coordination | Higher fees; risk of commission conflicts - do due diligence | Flat fee or AUM (negotiate & get it in writing) | Authorised firm & individual on DFSA/FSRA register; clear Retail/Professional classification. |
| DIY + coaching | Self-starters who want full control at low cost | Lowest costs; full transparency; skills for life | You’re responsible for execution & discipline | One-off coaching fee | Coaching is education, not regulated advice. |
Bottom line
In the UAE, regulation and fees are the two levers that separate genuine financial planning from expensive product sales.
The industry’s bad reputation, earned from years of commission-driven mis-selling, means you should approach any advisor with healthy skepticism. But as we’ve outlined, there are good advisors and firms operating here, and the regulatory environment is gradually improving to support investors.
For many investors, a simple ETF portfolio (with or without one-off coaching) is enough; when your situation is complex, use a DFSA/FSRA/CMA-authorised adviser whose incentives are aligned with yours.
Hope this helped, and feel free to reach out to us if you need any help!
Useful tools & resources
- Broker Warning List
- FIRE Calculator
- S&P 500 Calculator
- Compound Interest Calculator
- SimplyFI Getting Started Guide (DIY investing for UAE residents)